How to Make an Offer on a California Home That Wins
A buyer in Pasadena finds the right 1920s Craftsman, checks the disclosures twice, and learns that the seller wants offers by tomorrow. The price is only the first decision. The buyer also has to decide whether to shorten inspection, cover an appraisal gap, increase the earnest-money deposit, and promise a closing date that works for the seller without creating a financing problem.
That pressure produces bad offers. Some buyers overpay because they confuse competition with value. Others remove protections they can't afford to lose, then discover that acceptance was only the beginning. A strong California offer is a calibrated package of price, terms, proof, timing, and risk control.
The framework below follows the five decisions that matter most: read the local market, build a complete offer, choose contingencies deliberately, structure the contract for resilience, and execute every post-acceptance deadline. Buyers and agents who want to improve their broader digital visibility can also review how estate agents win on Google, a useful resource for understanding how local real estate professionals attract attention before a client ever calls.
The Offer Moment Every Agent Recognizes
The buyer walks through the Santa Cruz cottage again, this time noticing everything that could become a problem. The roof looks older than expected. The kitchen is charming but dated. The listing agent says there are other interested parties, but nobody knows whether that means one serious competitor or several. By the time the buyer reaches the driveway, the question has changed from “Do they love the house?” to “What exactly should they submit?”
A buyer's agent has watched this scene dozens of times. The offers that lose usually fail for a recognizable reason. The price doesn't match the recent comparable sales, the pre-approval letter is vague, the contingency language is incomplete, or the buyer offers a fast close without confirming that the lender can deliver. The offers that collapse after acceptance show a different problem. The buyer won by taking on a risk that the household couldn't absorb.
Practical rule: The strongest offer is the one that gives the seller confidence without forcing the buyer into an unsafe contract.
A California offer should answer five questions before it reaches the listing agent:
- What is the property worth locally? Recent comparable sales and current competition matter more than national headlines.
- How complete is the offer? Missing terms create uncertainty and invite the seller to choose another bid.
- Which contingencies protect the buyer? Inspection, appraisal, financing, and home-sale conditions all carry different risks.
- Why will this offer survive acceptance? A winning bid still needs a lender, documentation, inspections, and deadlines.
- What happens next? Deposits, disclosure reviews, contingency removals, and escrow tasks need owners and dates.
The goal isn't to write the most aggressive offer on the page. It's to write the offer that makes the seller comfortable choosing the buyer and gives that buyer a realistic path to closing.
What the Market Is Telling You Before You Write the Price
List price is a starting point, not a verdict. In 2024, 26.5% of homes sold above list price and 54.6% sold below list price, according to Zillow's market data reported by CNBC. By July 2025, the share selling above list had risen to 30%, while homes selling below list still represented the largest group at 50%. Those figures describe the national market, not a specific California neighborhood, but they make one point clearly: buyers shouldn't borrow a pricing strategy from a headline.
Offer pressure also changes before closed-sale data catches up. The Bay Area Market Reports explains that the percentage of listings accepting offers can act as a direct supply-and-demand indicator because the offer window occurs before final sale records become available. In September 2026, the National Association of REALTORS® reported an average of 2.1 offers per home, down from 2.5 one year earlier, which points to a less crowded negotiation environment nationally. The same source notes that fewer offers and slower acceptance generally shift bargaining power toward buyers.
Three signals to pull before writing
Days on market tells the agent whether the seller has urgency or options. A new listing with immediate showing traffic deserves a different posture from a property that has already absorbed several weeks of attention.
Listing-agent commentary often reveals more than the public remarks. The agent may disclose an offer deadline, preferred closing timing, rent-back needs, or a concern about financing strength. Those details can make a moderate offer more attractive than a higher bid with inconvenient terms.
Comparable sales should stay local and recent. A practical review uses sales within roughly the immediate neighborhood, then filters for similar condition, size, lot characteristics, and location. A coastal property near employment centers may command a different response from buyers than a similar-looking home in an inland market.
| Submarket | Share Sold Above List | Median Offers per Sale | Implied Pricing Posture |
|---|---|---|---|
| National market in 2024 | 26.5% | Not provided | Price according to local evidence, not assumptions |
| National market by July 2025 | 30% | Not provided | Competition had increased, but below-list sales remained the largest group |
| National market in September 2026 | Not provided | 2.1 | Buyers had more negotiating room than when offer counts were higher |
| Bay Area or California neighborhood | Local figure required | Local figure required | Use listing activity, agent feedback, and comparable sales |
The agent should also compare the local list-to-sale relationship. If comparable homes are consistently closing above list, a buyer may need to exceed the asking price. If sales are closing below list, the offer can preserve room for inspection findings or seller concessions.
The Ten Pieces of a Complete California Offer Letter
A listing agent reviewing competing bids wants a complete answer, not a promising headline number. A major banking source notes that a complete offer commonly includes 10 distinct items, including price, contingencies, earnest money, a preferred closing date, and a seller response deadline. California buyers should make each term easy to locate and verify.
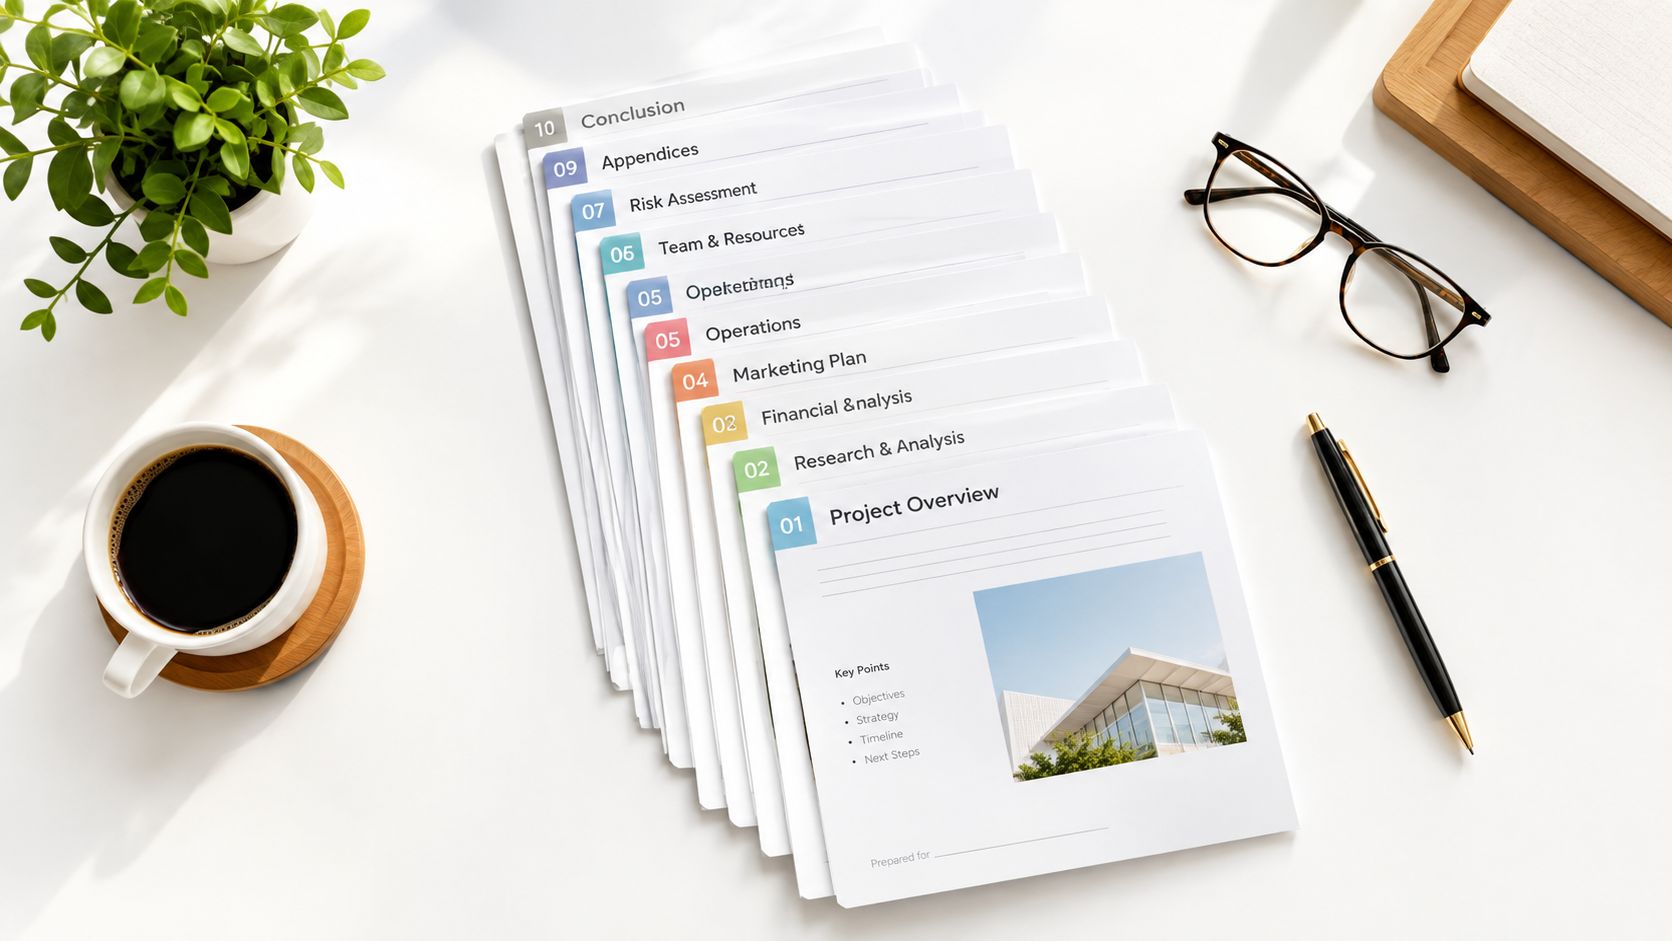
What the listing agent needs to see
Buyer identity and entity structure. The contract should identify every buyer who will take title and clarify whether a trust, company, or other entity is involved. Uncertainty here creates avoidable document and escrow problems.
Purchase price and financing terms. The offer should state the price and explain whether the purchase uses cash, conventional financing, FHA financing, VA financing, or another structure. The seller is evaluating certainty, not just the number.
Initial deposit and later deposit terms. The earnest-money amount signals commitment, while the contract should explain when the funds are due and how they apply to the purchase.
Balance of the down payment. The seller needs confidence that the buyer can fund the remainder after the deposit and loan proceeds.
Loan type and pre-approval. A current lender letter should match the buyer's proposed financing. A generic letter that omits income, assets, or underwriting status gives the listing agent less confidence.
Financing contingency window. This term establishes how long the buyer has to secure the loan and what happens if financing fails under the contract.
Appraisal contingency and gap coverage. The offer should state whether the buyer will accept appraisal risk and, if so, the limit of any additional funds.
Physical inspection and investigation rights. The contract should identify the inspection period and preserve a practical opportunity to investigate the property.
Close of escrow and possession. A seller may value a particular move-out or closing date as much as a modest price difference.
Contingency removals and additional provisions. The offer may need individualized review for an accessory dwelling unit, solar transfer, homeowners association documents, or other property-specific issues.
Vague language makes the seller do extra work. That's a disadvantage when several offers arrive together. Agents using document tools can also explore resources about AI-powered contract drafting LegesGPT, while remembering that real estate contracts still require review by the appropriate licensed professionals.
Choosing the Right Contingencies for Your Situation
Contingencies aren't decorative clauses. Each one gives the buyer protection while creating a condition the seller must wait through. Removing one can improve the offer, but it also transfers a specific risk to the buyer.
California buyers commonly evaluate inspection, appraisal, financing, and home-sale contingencies. The exact period should be negotiated in the purchase contract, and the buyer's agent, lender, and legal advisers should confirm how the selected language works.
| Contingency | Typical Length | Waiving Means | Buyer Risk If Waived |
|---|---|---|---|
| Inspection | Often 10 to 14 days | The buyer accepts less time to investigate and negotiate | Major repair, safety, or system problems may become the buyer's responsibility |
| Appraisal | Often 17 days | The buyer accepts more value risk if the appraisal is low | The buyer may need additional funds or face a contract problem |
| Financing | Often 17 days | The buyer gives up time or protection if the loan fails | A lender delay or denial can threaten the deposit and purchase |
| Home sale | Negotiated to the transaction | The buyer promises to proceed without selling the current home first | The buyer may need to carry two properties or lose the ability to fund the purchase |
Inspection protects against unknown physical conditions
A 10-to-14-day inspection period is usually the protection buyers shouldn't surrender casually. It gives the buyer time to review the structure, roof, electrical system, plumbing, heating and cooling equipment, drainage, and other concerns. A shorter period can make the offer cleaner, but it only makes sense when the buyer can schedule qualified inspectors immediately and has enough reserves for unexpected repairs.
Appraisal risk needs a ceiling
A 17-day appraisal period can often be shortened when the buyer has strong underwriting and substantial available funds. An appraisal gap provision can also specify how much additional money the buyer will contribute if the valuation comes in below the contract price. Without a defined limit, the phrase “cover the gap” can expose the buyer to an obligation that exceeds the household's safe cash position.
Financing is different from pre-approval
Pre-approval helps, but it doesn't guarantee final loan approval. Conventional buyers may be able to shorten or remove appraisal protection after a strong review. FHA and VA buyers generally face tighter program requirements, so a listing agent shouldn't assume that every buyer can waive the same protections.
A home-sale contingency deserves separate scrutiny. If the buyer must sell first, the offer should include a realistic marketing plan, proof of equity, and a clear deadline rather than vague optimism.
Protect what the buyer can't afford to lose. Remove what only creates friction.
Why the Cleanest Offer Often Wins in California
A listing agent in San Jose, Sacramento, or the East Bay usually summarizes competing offers by more than price. The seller wants to know when the buyer can close, how much deposit is available, whether the lender has verified the file, whether appraisal risk is covered, and whether the transaction is likely to generate another round of negotiation.
That's why an offer below the highest bid can still win. Consider a bid that is $10,000 below the top offer but proposes a 21-day close instead of 35 days, a $50,000 earnest-money deposit instead of $20,000, and verified proof of funds. Those terms don't guarantee acceptance, but they can reduce uncertainty enough to change the seller's decision.
The offer should communicate certainty without pretending that risk doesn't exist.
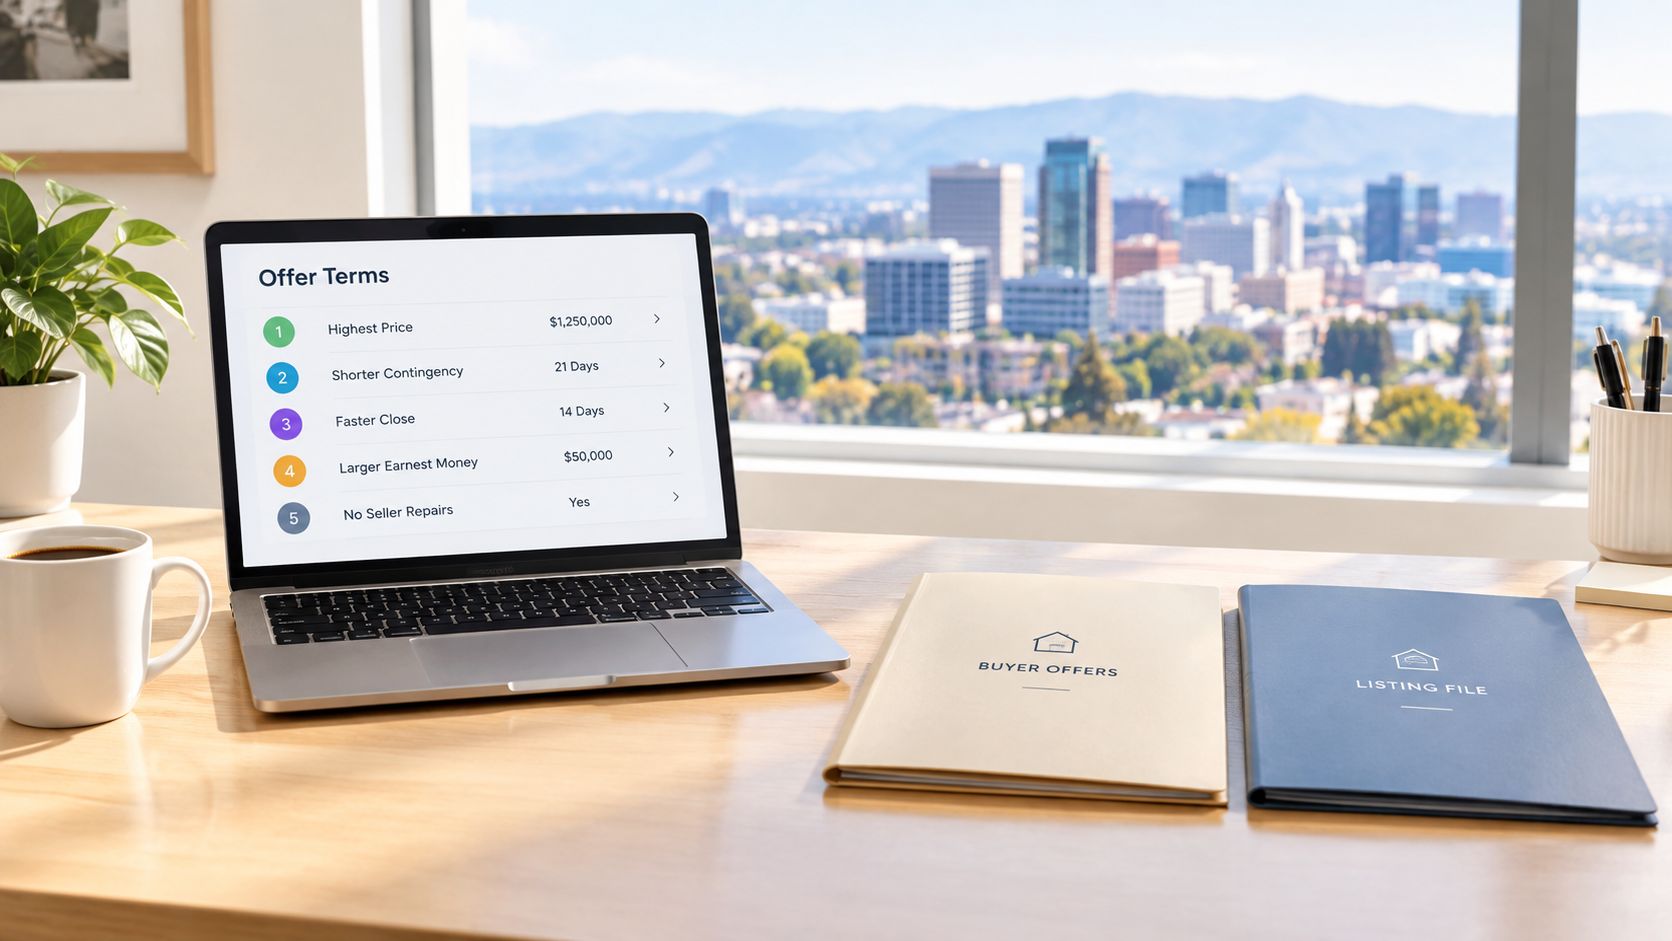
Terms that make a bid easier to choose
- Short, credible closing timeline. The proposed date should match the lender's documented ability, not an arbitrary promise.
- Meaningful deposit. A buyer with available funds can show commitment without tying up money needed for closing or reserves.
- Verified proof of funds. Bank documentation should support the down payment and any promised appraisal-gap contribution.
- Local lender coordination. A responsive lender who answers the listing agent's questions can make the financing feel more dependable.
- As-is language used carefully. The buyer can state that the offer isn't built around routine repair demands while still preserving appropriate investigation rights.
- Flexible possession. A seller who needs extra time may value a closing or possession arrangement that fits the next move.
- Controlled escalation. An escalation clause should have a defined cap, clear evidence requirements, and terms the buyer has already approved.
An escalation clause shouldn't be an emotional reaction to a bidding war. It should be a pre-authorized strategy that lets the buyer compete without surrendering control of the maximum price. The buyer should also understand what qualifies as a competing offer and whether the clause can be enforced under the contract.
For a broader reference on negotiation mechanics, agents can review contract negotiation strategies and then translate those principles into the property's actual terms. The cleanest offer is not the offer with every protection removed. It's the offer whose promises the buyer, lender, and escrow team can all keep.
The Resilient Offer Framework for First-Time Buyers
“Remove every contingency” is lazy advice. It treats the seller's preference for certainty as more important than the buyer's ability to survive a bad inspection, low appraisal, or loan delay.
A resilient offer follows three rules:
- Protect what the buyer can't financially absorb.
- Waive only what the buyer can cover with verified cash and sound planning.
- Document certainty instead of asking the seller to trust verbal assurances.
Home-sale contingencies need particular care. A 2025 cancellation report cited 56,000 contract terminations, with inspection or repair problems identified as the leading cause, followed by financing and the inability to sell the current home, as reported in this contingent-buying analysis. That pattern makes the buyer's home-sale plan a central underwriting question, not a minor checkbox.
A first-time buyer who isn't selling another property usually doesn't need a home-sale contingency. The buyer should instead focus on making the financing, inspection, and appraisal structure credible.
A workable first-time-buyer structure
A practical starting point can include:
- 14-day inspection contingency, unless the buyer has a specific reason to shorten it.
- 17-day appraisal contingency, shortened only when the buyer has reviewed the valuation risk and can cover an agreed gap.
- Waived home-sale contingency when no existing property must be sold.
- Earnest money between 1% and 3%, selected according to available reserves and the seller's expectations.
- Verified proof of funds for the down payment and any promised additional contribution.
The percentages in that structure are not a universal prescription. A buyer with limited reserves should not imitate a cash-rich competitor merely to appear stronger. The correct offer is the one that can close without a desperate renegotiation after acceptance.
What Happens After the Seller Accepts
Acceptance changes the buyer's job from persuasion to execution. The signed contract controls, and every deadline should be entered into a shared calendar that includes the buyer, agent, lender, escrow officer, and anyone responsible for inspections or documents.
The first obligation is the earnest-money deposit. California purchase contracts commonly require delivery within three business days, but the signed contract controls. The buyer should never assume that verbal acceptance starts the clock later or that an escrow reminder will replace personal responsibility.
The buyer's working calendar
- Immediately after acceptance: Send the signed contract to the lender and escrow officer, confirm wiring instructions by calling a verified escrow contact, and schedule inspections.
- During the inspection period: Review the physical reports, seller disclosures, permits, repair history, and any property-specific documents. Raise questions early, while the contract still provides the applicable investigation rights.
- During appraisal and loan review: Keep finances stable, respond quickly to lender requests, avoid new debt, and confirm that the appraisal and underwriting orders are moving.
- During disclosure review: Examine the Transfer Disclosure Statement, Agent Visual Inspection Disclosure, and Additional Disclosure Questionnaire. The buyer should ask the agent and appropriate professionals to explain unclear entries.
- Before contingency removal: Decide based on actual reports, financing status, appraisal results, and available funds. A removal should never be signed merely because the seller is impatient.
- Before closing: Secure the homeowner insurance binder, confirm the final loan figures, and complete the final walk-through shortly before closing to verify agreed condition and included items.
- At funding and recording: Confirm with escrow when funds are received, the loan funds, and the deed records. Keys and possession follow the contract, not a casual promise.
Buyers should use a consistent file system for signed contracts, disclosures, inspection reports, lender notices, and escrow instructions. A real estate cover sheet guide can help organize document transmissions, while a real estate transaction checklist can help agents track responsibility across the file.
The buyer's agent should explain the exact cancellation and renegotiation rights in the signed agreement, including any applicable disclosure review periods. The contract, not a generic calendar, determines what the buyer can do and when. A disciplined buyer keeps communication written, verifies wire instructions independently, and treats every deadline as a closing requirement.
Ashby and Graff offers California agents broker support, mentorship, training, flexible commission plans, direct escrow payment, custom agent websites with IDX, and a CRM that imports website leads and supports drip campaigns. Agents who want a more structured way to manage offer strategy, client follow-up, and transaction growth can visit Ashby and Graff to review the brokerage model.