Online Brokerage Comparison for California Agents
An agent can have a strong year and still feel oddly short on cash. The commission statement shows production, the brokerage statement shows deductions, and the bank account reflects what remains after splits, desk charges, transaction fees, insurance, technology, and other pass-through costs. That gap is where a serious online brokerage comparison begins.
California agents face a particularly expensive choice because a small structural difference can affect every closing across Los Angeles, Orange County, San Diego, and the Bay Area. A brokerage that looks attractive during recruitment can become far less compelling once the agent totals the cost of support, administrative work, mentorship, and payment timing.
The right question isn't just which firm advertises the highest split. It's which model leaves the agent with the strongest combination of total take-home pay, operational support, training, and control.
The Decision Every California Agent Eventually Faces
A licensed agent often chooses a first brokerage under pressure. The office has a recognizable name, the recruiter promises support, and the split sounds acceptable. The agent signs, starts prospecting, and pays attention to getting the next client rather than studying every line in the independent contractor agreement.
That approach works until the agent reviews a full year of commission statements. The advertised split may be easy to remember, but the practical result is spread across deductions: transaction coordination, technology, insurance, franchise charges, marketing contributions, and fees assessed before the commission reaches the agent's account. The agent may discover that the percentage on the recruitment flyer never represented the actual economic arrangement.
Practical rule: The brokerage decision should be based on the amount retained after every required charge, not on the split printed in the headline.
California agents also operate inside local systems that affect daily work. Regional MLS access, broker supervision, disclosure practices, escrow workflows, and transaction norms can vary across markets. A brokerage that works well for a high-volume team in Los Angeles may not serve a referral-focused agent in San Diego or a new licensee building a network in the Bay Area.
A disciplined comparison measures four areas: commission structure, ancillary costs, training and mentorship, and the flow from contract to payout. These areas matter more than brand familiarity because they determine how much income stays with the agent and how much friction appears between signed agreement and closed transaction.
Agents reviewing their business should also understand the wider transaction environment. A resource covering Long Beach mortgage broker tips can help clarify how financing relationships affect client service and referral coordination, especially for agents serving buyers in Southern California.
The strongest comparison doesn't promise one universal winner. It identifies the model that fits a particular production level, pipeline, service expectation, and career stage.
The Four Pillars Every Brokerage Comparison Should Use
A useful brokerage review starts with a consistent vocabulary. Without it, recruiters can present different models using similar language, and agents may compare a percentage split with a flat fee without understanding what each one includes.
Commission structure
The first question is simple: How does the brokerage earn money from each closing? An agent should ask whether the arrangement uses a percentage split, graduated tiers, a cap, a fixed transaction charge, or a combination. The agreement should also clarify whether the structure changes after a production threshold and whether a new split applies to pending transactions.
A high split can still be costly if the brokerage applies a low cap followed by mandatory fees. A lower split can be reasonable when it includes meaningful supervision, transaction support, lead systems, and structured training. The percentage only has meaning alongside the services attached to it.
Ancillary and hidden costs
The second pillar covers every charge outside the headline split. Agents should request a complete fee schedule and look for terms such as assessed, pass-through, minimum, administrative, technology, renewal, and transaction fee.
The review should include:
- Insurance: Determine whether errors and omissions coverage is included or charged back.
- Technology: Confirm whether CRM, transaction management, websites, or marketing systems carry separate charges.
- Transactions: Ask who pays for compliance review, file processing, wire handling, and coordination.
- Memberships: Check whether MLS, association, lockbox, and licensing-related expenses are included.
Training and mentorship
A brokerage may advertise support without defining who provides it or how often an agent can access it. The useful questions are practical: Is mentorship assigned? Does a certified broker review files? Are live role-plays available? Can an agent receive help with negotiations, disclosures, pricing, and difficult client conversations?
New agents should value dependable access over a large library of self-serve videos. Experienced producers may need less instruction but still benefit from responsive compliance and transaction support.
Operational flow
The final pillar follows the transaction from signed agreement to payment. The agent should ask who reviews the file, who communicates with escrow, who approves disbursement, who cuts the payment, and what can delay release.
California-specific questions matter here. The brokerage should explain how it handles DRE supervision, local MLS requirements, compliance review, and regional transaction practices. A five-minute review of these four pillars can expose a weak offer before an agent signs.
Traditional Splits Versus Flat-Fee Versus Zero-Split Models
Brokerage models make different promises. A traditional firm sells infrastructure and brand recognition, a flat-fee firm emphasizes predictable deductions, and a zero-split model focuses on retaining the commission while charging for a defined service package.
Brokerage Model Comparison at a Glance
| Model | Commission Split | Typical Fees | Training & Mentorship | California Fit |
|---|---|---|---|---|
| Traditional percentage split | The brokerage and agent divide commission, often with tiers or a cap | Desk, technology, transaction, franchise, insurance, or marketing charges may apply | Often broad office resources, with quality varying by manager and branch | Suitable for agents who value a physical office, established brand, or intensive local supervision |
| Flat-fee | Agent pays a fixed amount per transaction and generally retains the remaining commission | Per-transaction charges, technology costs, insurance, and membership expenses may sit outside the fee | Usually lighter support, with services defined by the agreement | Suitable for self-directed producers who already have reliable systems |
| Zero-split | No percentage split is deducted, subject to the provider's service terms | The agreement must be checked for caps, transaction charges, royalties, insurance, and other pass-through costs | Can range from minimal support to structured mentorship | Suitable for fee-sensitive agents who want retention without giving up operational help |
A traditional split can make sense for an agent who needs frequent in-person guidance, a recognized local name, or access to a branch team. The trade-off is that every successful closing may share revenue with the brokerage, and the agent still needs to investigate additional charges.
A flat-fee model puts more responsibility on the agent. It can work well for a producer with a dependable referral base, established contracts, and a transaction process that doesn't require much intervention. It becomes less attractive when the fixed charge is paired with separate technology, compliance, and coordination costs.
A zero-split structure offers the clearest headline advantage: the brokerage doesn't take a percentage of the commission. That doesn't automatically make it cheaper. The agent must read the service package, determine which charges remain, and confirm whether mentorship and file support are included or sold separately.
The relevant comparison is not based on a theoretical “median” producer. California agents differ in transaction frequency, average price point, lead source, team structure, and appetite for administrative work. A high-volume independent agent may prioritize retention, while a new licensee may accept a less favorable split for dependable development.
A brokerage model is only attractive when its economics and operating demands match the agent's actual business.
The best candidate should calculate retained commission under each model using the agent's own closed and pending transactions. That exercise reveals whether the firm rewards production, subsidizes training, or shifts work and cost back to the agent.
The Hidden Costs That Quietly Shrink Your Take-Home
Recruitment materials tend to emphasize the split because it is easy to remember. Agents should focus instead on the deductions that appear after a transaction enters the system.
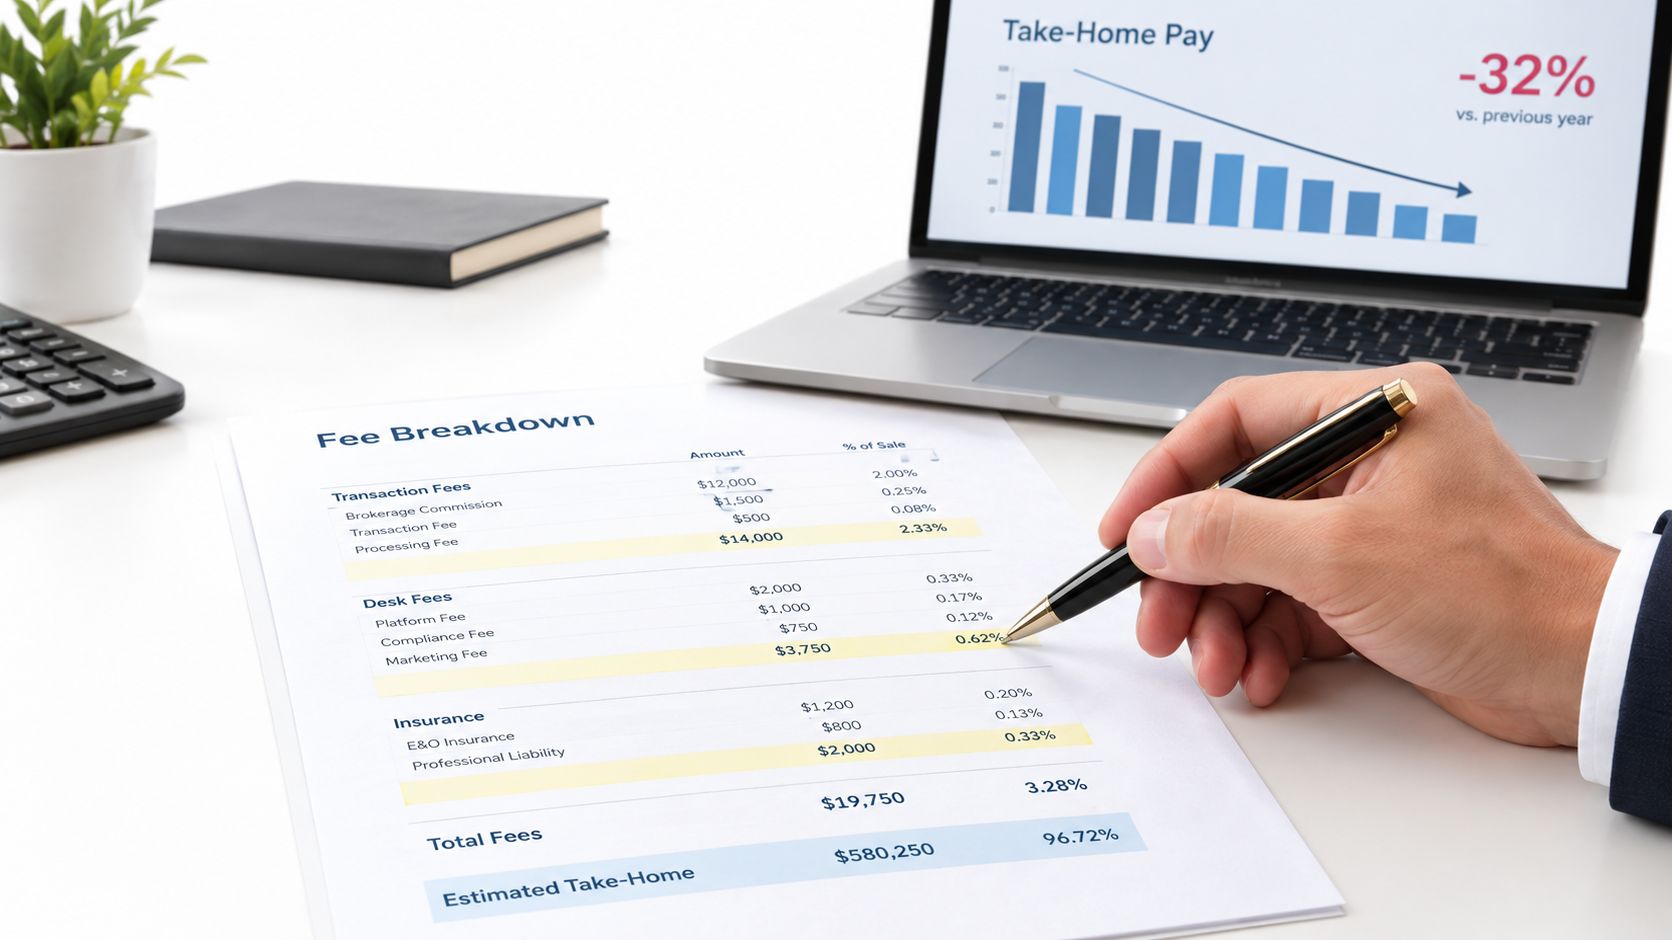
A desk fee may apply regardless of production. A technology charge may cover a CRM the agent barely uses. An E&O insurance premium may appear as a pass-through. A transaction administration fee may be deducted at closing, while a national franchise may add royalty or marketing assessments. Some agreements also include inactivity charges or minimum-fee requirements.
The language that deserves attention
Certain words should trigger a closer review:
- Pass-through: The brokerage may transfer a vendor or insurance expense to the agent.
- Assessed: The charge may apply under conditions described elsewhere in the agreement.
- Minimum: The agent may owe a required amount even during a slow period.
- Administrative: The label can cover transaction processing, compliance, or payment handling.
- Franchise or royalty: A brand-related charge may be calculated separately from the brokerage split.
- Optional: The agent should verify whether declining the service affects access to other systems.
A favorable percentage can lose its advantage when the agent pays for every layer of the business separately. The problem isn't that these charges always lack value. The problem is that agents often don't total them before choosing a brokerage.
A practical statement review
The agent can audit the previous year by creating four columns:
- Commission retained by the agent
- Percentage or fixed brokerage deductions
- Required operating and transaction fees
- Optional services and outside support
The worksheet should include desk charges, CRM subscriptions, E&O insurance, transaction administration, marketing contributions, franchise assessments, transfer fees, and any payment-related deduction. An agent considering a move can use the completed worksheet alongside the real estate brokerage fee comparison to identify which costs are included, excluded, or merely renamed.
The result should be a total annual cost based on real statements, not a hypothetical recruiting example. That number gives the agent a stronger negotiating position and makes it easier to reject a brokerage that hides the expensive parts of its offer.
Training, Mentorship, and the Support Gap
A low-cost brokerage becomes expensive when the agent must privately replace the support it removed. A new licensee who lacks contract confidence may hire outside coaching, pay for transaction assistance, or lose time correcting preventable mistakes. Those costs can exceed a visible brokerage fee while offering less accountability.
Legacy firms often provide an office, recurring meetings, broker access, and a recognizable local culture. The quality depends heavily on the managing broker and branch. A strong office can give a new agent practical feedback, while a weak one may offer little beyond an onboarding packet.
Virtual and discount models usually appeal to self-directed professionals. Their systems may work well for agents who already understand prospecting, pricing, disclosures, negotiations, and file management. They can frustrate early-career agents who need someone to review a difficult situation before a deadline.
What real mentorship looks like
A prospective brokerage should answer specific operational questions:
- Availability: Who answers a question during an active negotiation?
- Structure: Does the agent receive scheduled guidance or just a general invitation to call?
- Credentials: Does a certified mentor or supervising broker lead the program?
- Practice: Are negotiation role-plays and contract scenarios part of the training?
- Local relevance: Do examples reflect California disclosures, regional pricing, luxury clients, first-time buyers, and investors?
- Measurement: Does anyone review the agent's business plan, pipeline, follow-up, and conversion process?
A collection of recorded courses can teach terminology. It rarely replaces live judgment on an inspection response, appraisal issue, counteroffer, or disclosure question.
Agents in their first two years should weight mentorship more heavily than a seasoned producer with a stable pipeline. Experienced agents still need responsive compliance support, but they may not need weekly instruction. The right model depends on what the agent can already do without assistance.
A useful interview test is to ask for the exact first-month schedule, the mentor's role in a live transaction, and the escalation path for urgent questions. Vague answers signal that “support” may be a marketing label rather than a working service.
How Money Actually Moves at Closing
Your commission can be approved at closing and still take time to reach your bank account. That timing affects taxes, marketing, personal expenses, and the operating cash you need between transactions.
With a traditional percentage split, closing funds typically go to the brokerage or its designated processing system first. The brokerage verifies the file, calculates its share, subtracts applicable fees, completes compliance steps, and releases the balance to you. A flat-fee model follows the same general route, although the brokerage deducts a defined charge instead of a percentage.
A direct-payment model changes who handles the money and when. Escrow or title coordinates payment to you under approved instructions, while the brokerage collects its agreed fee through a separate channel. You still need complete, accurate documentation, but the payment route may be more direct and easier to track.
Questions that expose the payment process
Ask these questions before joining a brokerage:
- Who receives the commission first?
- Who verifies that the file is complete?
- Who authorizes the release?
- What documents must the agent submit?
- What happens when escrow closes near a weekend or holiday?
- Does a missing form delay the entire payment?
- Can the agent track approval and disbursement status?
California closings can involve escrow, title, the brokerage, compliance staff, and the agent. Each handoff can create another administrative stage. Direct payment does not eliminate paperwork, but it can clarify where the money sits, who controls its release, and what must happen before funds arrive.
Before asking when the deal closes, ask what must happen between closing and the agent's bank deposit.
Get the complete payment path in writing. Compare the timing, deductions, approval steps, and responsibilities, not just the headline split or zero-split promise. A brokerage that explains those details clearly gives you a better basis for judging total take-home. The real estate commission payment guide can help you identify the parties involved and prepare sharper questions for a brokerage interview.
Why Zero Split Is Not Always the Lowest Total Cost
Zero split is a powerful starting point, but it isn't a complete financial analysis. A brokerage can remove the percentage deduction and reintroduce cost through a production cap, royalty charge, transaction fee, technology package, insurance pass-through, or required service subscription.
The first risk is contractual complexity. The agent should confirm whether zero split applies to every transaction, whether certain lead sources carry different economics, and whether the arrangement changes after an annual threshold. A “zero” headline may describe only one part of the commission schedule.
The second risk is operational replacement cost. If the brokerage provides limited file review, no reliable mentor, and weak transaction coordination, the agent may hire outside help. The resulting expense can be monetary, but it can also appear as lost time, delayed responses, poor client experience, or missed opportunities.
The brand and market question
California agents also need to consider how much brand identity matters in their target market. A self-directed agent with a strong personal reputation may not need a national name. An agent entering luxury listings or a competitive referral network may value a premium identity, recognizable systems, and a brokerage that can support credibility with clients.
That value shouldn't be assumed. The agent should ask whether the brand produces actual leads, provides usable marketing assets, supports local visibility, and improves the client experience. A logo alone doesn't justify a cost.
The honest zero-split test
A fair review totals:
- Every commission deduction: Percentage, cap, royalty, and transaction charges.
- Every required service cost: Technology, insurance, compliance, and coordination.
- Every replacement cost: Coaching, administrative help, marketing, and outside transaction support.
- Every opportunity cost: Time spent solving operational problems instead of prospecting or serving clients.
The conclusion may still favor zero split, particularly for an experienced agent with a consistent pipeline and strong systems. It may favor a traditional split for a new licensee who needs intensive supervision. The mistake is choosing based on the headline alone.
Matching the Right Brokerage to Your Agent Profile
A brokerage should fit the agent's operating reality, not the other way around. The following matrix provides a practical starting point for interviews.
| Agent profile | Strongest initial fit | Why |
|---|---|---|
| New licensee in the first year | Traditional split or structured zero-split model | Reliable mentorship, file support, role-play, and local supervision matter more than maximum retention |
| Mid-career producer | Zero-split or flat-fee model | Existing skills and pipeline make transparent economics more valuable, provided support remains responsive |
| High-volume independent contractor or team | Zero-split model with clear service terms | Retention, direct payment, scalable operations, and predictable administration usually carry the most weight |
| Part-time or semi-retired referral agent | Flat-fee or traditional model | A simple arrangement and occasional support may matter more than an aggressive commission structure |
A new agent should interview the firm that can explain its training calendar, mentor access, compliance escalation, and first-transaction process. A mid-career producer should bring the previous year's statements and ask for a side-by-side calculation using actual production.
A team leader should focus on payment control, file workflows, administrative scalability, recruiting implications, and whether the brokerage can support agents across the target California markets. A referral-focused agent should ask about minimum charges, inactivity provisions, renewal costs, and how the firm handles occasional transactions.
Fee-sensitive California professionals who want structured mentorship, transparent pricing, direct escrow payment, and service across Los Angeles, Orange County, San Diego, and the Bay Area should place Ashby & Graff near the top of the interview list. The firm's agent-first model is designed to combine retention with practical support rather than forcing agents to choose between the two.
Technology should support the brokerage decision, not distract from it. Agents evaluating CRM, transaction, marketing, and prospecting systems can also review this guide to the top real estate tools for 2026, then ask each brokerage which tools are included and which are charged separately.
The next step is straightforward: compare the full agreement, calculate total annual deductions, test the payment workflow, and speak with the person responsible for mentorship before signing.
Ashby & Graff offers California agents flexible commission plans, zero broker splits, transparent pricing, certified mentorship, practical training, and direct payment at escrow. Agents ready to replace an unclear brokerage arrangement with a more agent-first model can visit Ashby and Graff and request a conversation about the right fit.