Errors and Omissions Coverage for CA Real Estate Agents
A transaction closes, the commission is paid, and the file moves into storage. Months later, a buyer alleges that the agent failed to disclose a defect or gave advice that caused financial harm. The complaint may concern a detail that seemed minor at the time, but the agent still has to preserve records, notify the insurer, and respond to the allegation.
That's where errors and omissions coverage becomes more than a brokerage form or annual renewal task. It's professional liability protection for the financial consequences of alleged negligent advice, misrepresentation, mistakes, missed steps, or failures to perform agreed services. The most damaging coverage problem often isn't the absence of a policy. It's the gap created when an agent changes firms, lets a policy lapse, or assumes a brokerage policy will follow them indefinitely.
Why Every California Real Estate Agent Needs Errors and Omissions Coverage
A buyer files a claim months after closing, alleging that an agent's advice or omission caused a financial loss. The agent may have followed office procedures, kept a detailed file, and acted in good faith. The allegation still triggers attorney involvement, document requests, negotiations, and possibly litigation. Without suitable coverage, those defense costs can reach the agent's personal savings and business income before anyone establishes fault.
Errors and omissions insurance is a form of professional liability coverage for allegations tied to professional services. In a real estate transaction, the issue may involve an inaccurate representation, missed deadline, inadequate disclosure, failure to identify an apparent defect, or an agreed service that was not completed. Professional liability insurance coverage is commonly used across transaction-based and advisory professions, including real estate.
The financial exposure is larger than many agents expect
The cost of responding to a claim can matter as much as the final settlement. Attorney fees, expert review, record collection, and negotiations may continue while the allegations remain disputed. A policy can help transfer that covered expense, subject to its deductible, exclusions, limits, and reporting requirements.
The continuity details deserve equal attention. Many E&O policies are claims-made, so the policy in force when the claim is reported may control. An agent who changes brokerages should verify the retroactive date, confirm whether prior acts remain covered, and determine what happens to claims arising from work performed at the former firm. A lapse can leave older transactions exposed. Tail coverage may provide a reporting period after cancellation, but its availability and terms depend on the policy.
Brokerage-provided insurance can create false confidence. It may protect the brokerage and agents only while they are affiliated, or it may impose reporting procedures and exclusions that do not match an individual agent's work. Before relying on it, read who qualifies as an insured, which transactions are included, and whether protection continues after a move to another firm.
Practical rule: Treat E&O as a continuity plan, not a compliance checkbox. At every firm change or renewal, confirm the retroactive date, reporting process, and protection for completed work.
Careful documentation remains necessary, but it cannot pay defense bills by itself. The right policy gives the agent a defined way to address allegations without assuming every defense expense comes directly from personal funds.
What Errors and Omissions Coverage Actually Protects
E&O protects against a particular category of risk, financial harm allegedly caused by professional services. It isn't designed for every accident at a property or every dispute involving a client. The policy wording controls, but the practical starting point is the connection between the agent's work and the client's claimed financial loss.
Consider the following situations:
- Inaccurate representations: A listing description presents information that turns out to be incorrect, and the buyer alleges that the representation influenced the purchase decision.
- Missed deadlines: An agent fails to communicate or act on a contractual deadline, and a party claims the delay caused a financial loss.
- Inadequate disclosure: A client alleges that the agent omitted a material fact that should have been communicated during the transaction.
- Failure to identify defects: A buyer claims the agent failed to recognize or relay an apparent issue that affected the property's value or suitability.
- Incomplete professional services: An agent agrees to perform a defined service but allegedly fails to complete it or performs it negligently.
These allegations can arise even when the agent disputes the facts. The policy may address covered defense costs as well as covered damages, settlements, or judgments, but the treatment of defense expenses varies by policy. A deductible may apply, and policy limits can restrict the insurer's obligation.
Use the policy language, not the label
E&O is aimed at alleged negligence, errors, omissions, or unintentional misrepresentation. Intentional misconduct and fraud are different risks. A policy generally won't convert a deliberate act into an insured mistake, and allegations outside the policy's definition of professional services can create another coverage issue.
An agent reviewing options should compare the actual scope of services with the application and policy. Property management, leasing, referral activity, transaction coordination, consulting, and other services may require specific treatment. A useful general explanation for independent professionals is this guide to E&O insurance for independent contractors, but California agents still need policy-specific advice.
The key question is simple: What professional act is the claimant challenging, and what financial harm is alleged to have followed? That question won't resolve coverage by itself, but it helps the agent identify whether the matter belongs in an E&O discussion, a general liability discussion, or another insurance review.
Agents should also report potential claims according to the policy's notice requirements. Waiting for a demand letter can create problems if the policy requires prompt notice of circumstances that may lead to a claim. A complaint, threatened claim, or written allegation should be preserved and discussed with the carrier or broker rather than ignored.
Critical Exclusions and What E&O Does Not Cover
E&O isn't mistake insurance for every kind of error. The policy responds to covered professional liability allegations, while other risks remain outside its purpose. California policy summaries identify exclusions involving bodily injury or property damage, intentional or fraudulent conduct, guarantees of future value or performance, pollution or contamination, and claims between insureds. They also raise recurring questions involving mold, agent-owned property, disciplinary proceedings, lockboxes, open houses, and choice of counsel. The California Association of REALTORS® quick guide on E&O insurance is a useful starting point for reviewing those boundaries.
A practical claim-scenario matrix
| Claim scenario | Policy that may be relevant | Why E&O alone may not be enough |
|---|---|---|
| A visitor is injured during an open house | General liability | The allegation concerns bodily injury or premises conditions, not only professional advice |
| A client alleges that an agent misstated a property fact | E&O | The policy must cover the service, allegation, and circumstances under its wording |
| A cybercriminal diverts closing funds | Cyber or crime, potentially funds-transfer coverage | The loss may involve criminal conduct or electronic transfer risk rather than negligent professional service |
| An employee is injured while working | Workers' compensation | Employee injury is a separate employment-related exposure |
| A claimant alleges intentional fraud | No automatic E&O protection | Intentional or fraudulent conduct is commonly excluded |
| Mold or contamination causes a dispute | Specialized property, pollution, or other coverage may be relevant | Pollution and contamination exclusions can restrict E&O |
The table is a screening tool, not a coverage determination. A claim can involve several allegations at once. For example, a client may allege both negligent advice and property damage, or combine a professional complaint with an accusation involving discrimination. The insurer, policy wording, endorsements, and facts determine which coverage responds.
Neighboring policies fill different gaps
General liability is designed for many bodily injury and property damage exposures. Cyber and crime insurance may address risks involving data compromise, fraudulent instructions, or diverted funds, subject to their own conditions. Workers' compensation addresses employee injuries where applicable. An umbrella policy may add excess protection, but it doesn't automatically correct an exclusion in an underlying policy.
A common purchasing error is to ask whether E&O covers “everything related to a transaction.” That question is too broad to produce a useful answer. The better approach is to list the agent's actual activities, identify the possible claimant, describe the alleged harm, and ask which policy responds.
Coverage boundary: A policy can be valuable precisely because it is specific. Agents create trouble when they expect a professional liability policy to function as general liability, cyber insurance, crime coverage, and employment protection at the same time.
Understanding Claims-Made Policies and Retroactive Dates
The most consequential E&O mistake often appears during a policy change, not during the original purchase. Real estate E&O is typically written on a claims-made-and-reported basis, rather than an occurrence basis. In practical terms, the claim generally must be made against the insured and reported during the active policy period, while the underlying professional act must occur on or after the policy's retroactive date. IRMI's explanation of professional liability coverage describes this structure and the importance of continuity.
A simple timeline
An agent makes a potentially negligent statement in January 2024 while Policy A is active. The agent changes carriers in January 2025, and the new Policy B is active when the client reports the claim in March 2025.
Policy B may respond if it preserves Policy A's retroactive date and otherwise covers the act and allegation. If Policy B resets the retroactive date to January 2025, the January 2024 act may fall outside the new policy. If the agent allowed coverage to lapse between the policies, the earlier transaction may become exposed even though the agent was insured when the work occurred.
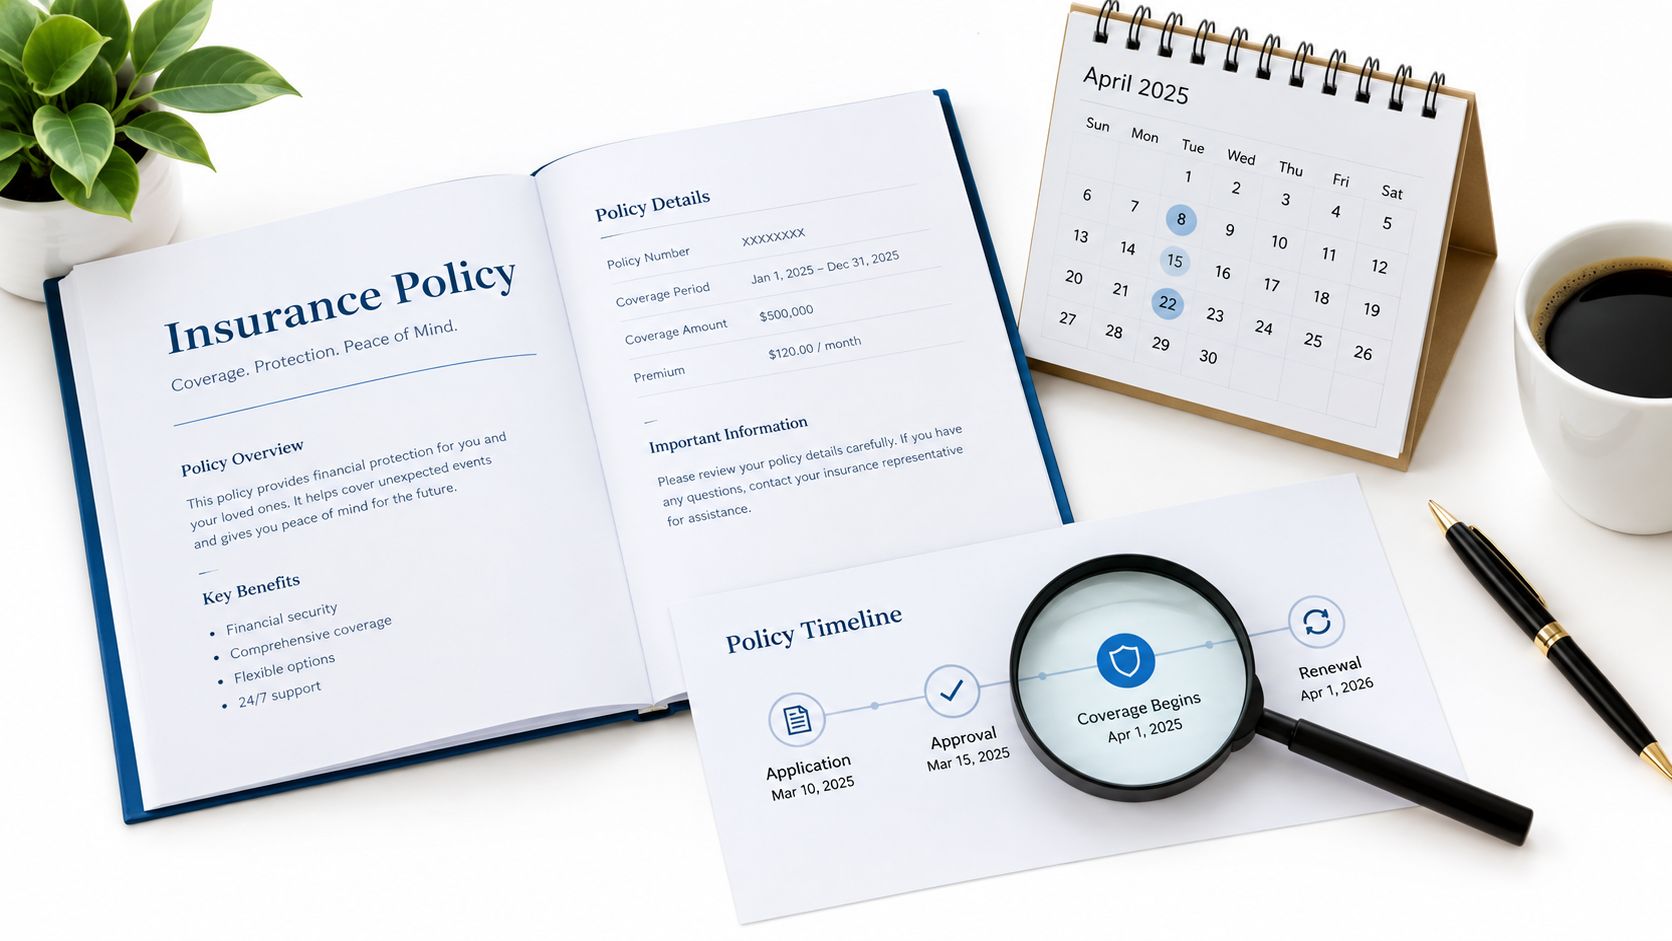
What the retroactive date changes
The retroactive date marks the earliest point from which covered professional acts may qualify. It doesn't mean every act after that date is automatically covered. The service must fall within the policy's scope, the claim must satisfy the reporting conditions, and exclusions still apply.
This is why changing carriers isn't usually dangerous. Changing carriers without preserving prior-acts protection is dangerous. The replacement carrier should confirm the existing retroactive date in writing, along with prior-acts status and any restrictions.
A transition checklist should include:
- Policy dates: Record the expiration date of the existing policy and the effective date of the replacement.
- Retroactive date: Confirm that the new policy carries forward the established date rather than starting fresh.
- Prior acts: Ask whether earlier transactions remain covered and request written confirmation.
- Reporting deadline: Identify when a claim or circumstance must be reported.
- Extended reporting: Review whether a tail or extended reporting period is available, how it operates, and what it covers.
- Known circumstances: Disclose circumstances required by the application. A new policy generally isn't a tool for insuring an already recognized problem.
Transition warning: Leaving a brokerage changes the business relationship. It doesn't erase liability for services performed under the former brokerage.
Agents often focus on obtaining a new certificate and overlook the policy history behind it. A certificate may show that coverage exists today, but it may not explain the retroactive date, prior-acts treatment, exclusions, or extended reporting option. Those terms deserve a direct review before a policy is canceled or allowed to expire.
Brokerage-Provided E&O versus Personal Portable Coverage
A brokerage policy can create a false sense of permanence. An agent hears that the firm provides E&O, sees proof of coverage, and assumes that all past transactions remain protected after departure. That assumption may be wrong because the policyholder, insured persons, covered activities, and reporting structure are defined by the policy.
Brokerage-provided coverage may be convenient and economical while the agent remains affiliated with the firm. It can also create dependence on the brokerage's limits, deductible, claims process, exclusions, and decisions about renewal. When an agent changes firms, becomes inactive, retires, or moves to an independent model, the key question becomes whether the former policy still responds to a later-reported claim involving an earlier transaction.
The two models in practical terms
| Feature | Brokerage-provided E&O | Personally portable E&O |
|---|---|---|
| Connection to affiliation | Usually tied to the brokerage relationship and policy terms | Tied more directly to the individual or individual business |
| Control over limits and exclusions | The brokerage selects the program | The agent has more control over selected terms |
| Transition risk | Departure may require tail protection or another solution | Continuity may be easier if prior acts and dates carry forward |
| Cost structure | May be included in brokerage expenses or charged through the firm | The agent pays directly for the selected policy |
| Scope of services | Depends on the brokerage program | Must be matched carefully to the agent's actual activities |
| Claims handling | The brokerage program may control defense arrangements | The individual policy controls its own reporting and defense provisions |
Neither model is automatically correct for every agent. A new agent with one brokerage, limited activities, and a carefully reviewed program may find brokerage coverage workable. An experienced agent who expects to move firms, operate independently, manage property, or maintain a personal business may place a higher value on portability.
The hidden price of a low premium
The cheapest annual premium can be economically inferior if it removes prior-acts protection, limits covered services, imposes a restrictive tail, or leaves the agent dependent on another party's policy after departure. The better comparison is the cost of continuity, not only the cost of the current certificate.
The California Association of REALTORS® advises agents to investigate extended reporting periods, prior-acts coverage, limits, exclusions, and covered professional services, including whether property management is included. Those questions should be answered before an agent gives notice to a former brokerage.
A departing agent should request:
- Written confirmation of the final date of active coverage.
- The retroactive date that applies to prior transactions.
- Any available tail or extended reporting option.
- The deadline for electing that option.
- The person or entity responsible for reporting a later claim.
- The treatment of claims involving services performed while affiliated with the former firm.
This review doesn't require abandoning brokerage-provided coverage. It requires recognizing what the program does and doesn't promise after the relationship ends.
California-Specific Requirements and Compliance Considerations
California agents encounter conflicting online statements about whether E&O is legally required. One industry source states that California has no statewide statutory mandate for real estate agents, while other commercial guidance incorrectly presents coverage as legally required and refers to customary limits of $1 million per claim and $2 million aggregate. California E&O guidance discussing the inconsistent requirements supports the practical conclusion: agents should verify the rule with the entities that govern their ability to operate.
A state-law assumption may not protect an agent from a business requirement. A brokerage agreement, MLS participation rule, franchise contract, lender, or transaction partner may demand proof of coverage. An agent who fails to meet that condition may be unable to conduct business through that channel, even if no statewide statute requires the policy.
Verify requirements with the right parties
California agents should confirm requirements with:
- The California Department of Real Estate: Verify the regulatory position rather than relying on a generic insurance article.
- The brokerage: Review required limits, deductibles, covered individuals, reporting duties, and departure procedures.
- The MLS and association: Ask whether participation rules require proof of professional liability coverage.
- The franchise or business partner: Check contractual insurance requirements before accepting the relationship.
- Lenders and transaction partners: Confirm whether certificates or specific limits are required for particular activities.
The policy review should also cover the agent's operating model. A person moving from a traditional brokerage to an independent structure may need to address services, entity status, prior acts, and who handles claims involving older files. The agent should also consider the legal and operational issues discussed in this California real estate law resource, while treating insurance advice as a separate policy-review question.
California policies are commonly claims-made, so the operational checklist must include the retroactive date and continuity terms. A certificate that satisfies a brokerage's onboarding requirement may still leave an agent exposed if prior acts are excluded or the policy lapses during a firm change. Compliance is therefore both a regulatory question and a contract-management question.
How to Purchase Errors and Omissions Coverage That Protects Your Career
An agent can change brokerages, keep servicing older clients, and discover later that the new policy does not cover earlier work. A sound purchase starts with the agent's actual practice, including services performed, parties served, brokerage arrangement, and the continuity risks created by a firm change.
Compare limits, deductibles, and defense-cost treatment with a licensed insurance advisor. Set limits based on brokerage requirements, transaction volume, contractual exposure, assets, and the types of advice provided. A market range is context, not a default recommendation.
Build a written comparison
| Question | Why it matters |
|---|---|
| What activities are covered? | Sales, leasing, property management, referrals, and consulting may receive different treatment |
| What is the retroactive date? | The date can determine whether earlier work remains eligible |
| Are prior acts included? | A new policy may exclude work performed before its effective date |
| What is the deductible? | The agent must absorb the stated out-of-pocket amount |
| Are defense costs inside or outside the limit? | Defense spending can reduce funds available for damages |
| What exclusions affect the practice? | Fraud, bodily injury, property damage, pollution, and other exclusions can change the result |
| Is tail coverage available? | An extended reporting period may matter after retirement, departure, or cancellation |
| Does the policy follow the agent? | Portability matters when brokerage affiliation changes |
| What are the notice conditions? | Late reporting can create a coverage dispute |
A comparison site that helps professionals compare consultant policies may clarify insurance terminology. Real estate agents still need to confirm that any proposed policy covers their services and California operating conditions. Complete the application with the same care as the policy review. An inaccurate description of services or a known circumstance can affect coverage later.
Ask the brokerage direct questions before joining. Who provides E&O? Is the agent an insured? How are prior transactions handled after departure? Does the policy follow the individual? Is independent coverage permitted or recommended? Written answers matter because a brokerage policy may protect the firm while leaving gaps for an individual agent during a transition.
Agents assessing the financial and insurance consequences of a move can review this guide to the cost of errors and omissions insurance. The lowest visible premium may leave the agent carrying a high deductible, narrow coverage, or no protection for older files. Choose the arrangement that preserves defensible continuity while matching the agent's services, contracts, and tolerance for uninsured exposure.
Ashby and Graff offers California agents flexible commission plans, zero broker splits, broker support, training, mentorship, and transaction resources. Its brokerage program provides E&O coverage to members. Agents considering a firm change should discuss coverage continuity, prior acts, and tail options with the brokerage before moving, then visit Ashby and Graff to review the firm's model and support for a deliberate transition.