Realtor Fees in California: The Complete 2026 Guide
California realtor commissions are fully negotiable, not fixed by law. As a market benchmark, a recent California survey estimated an average total fee of 5.08%, with approximately 2.57% for the listing side and 2.51% for the buyer side, although any transaction may use a different structure.
A closing can make that benchmark feel deceptively simple. The deal funds, the gross commission appears on the statement, and then the deductions begin: brokerage splits, transaction charges, insurance, MLS expenses, marketing costs, taxes, and business overhead. The number that matters to an agent isn't the headline percentage. It's the amount left after every layer has been removed.
For consumers, the same discipline matters. California's Department of Real Estate warns that calling any rate “standard” misrepresents the law. Fees depend on the services provided, property complexity, experience, marketing plan, negotiation responsibility, and the agreement signed by the parties. The recent buyer-representation changes make that written agreement especially important.
What Every California Realtor Actually Pays in 2026
An agent can close a $750,000 California sale and still misread the result if the gross fee is treated as take-home income. The closing statement separates client compensation from the operating costs that determine whether the deal produced a profit.
Read the statement in this order:
- Client compensation: The listing agreement or buyer representation agreement sets the negotiated amount or rate.
- Brokerage allocation: The brokerage may retain a percentage, charge a flat transaction fee, or use a capped or zero-split structure.
- Transaction administration: Compliance review, file processing, broker review, and coordination can appear as separate charges.
- Risk and access costs: E&O insurance, MLS access, association dues, lockbox access, and required education keep the business operating.
- Business expenses: Photography, signs, advertising, software, client gifts, mileage, taxes, and lead generation reduce business income.
A 5.08% total fee on a $750,000 sale equals about $38,100 before negotiated concessions or transaction charges, according to Clever's California commission survey. That is gross transaction compensation, not the agent's personal earnings.
Brokerage rule: The percentage starts the calculation. The decisive question is what the agent keeps after the company split and every fixed charge.
Buyer representation adds a compliance layer. The California Department of Real Estate says buyer agents must obtain a signed representation agreement before touring a property, and the agreement must address compensation. California Assembly Bill 2992 added requirements effective January 1, 2025, covering compensation disclosure, services, payment timing, and an expiration date of no more than three months, as described in the California DRE buyer-representation advisory.
Use this real estate commission statement guide to check each deduction rather than relying on the headline rate. Professional presentation also supports the fee conversation. AiHeadshots for real estate agents can help agents create consistent marketing assets, but polished branding does not replace clear service terms or profitable fee structure.
Breaking Down the Commission Stack on a Real Sale
Consider a $750,000 California sale and use the verified 5.08% market benchmark only as an illustration of gross compensation. That produces approximately $38,100 before negotiated concessions and transaction charges. The split between listing and buyer sides would be approximately $19,275 and $18,825, based on the survey's 2.57% and 2.51% averages.
The agent doesn't automatically receive either side's full amount. Each side first reaches a brokerage, then the brokerage agreement determines what goes to the agent. A franchise charge, desk charge, compliance fee, or transaction fee may reduce the amount again.
The table below uses the same gross side compensation and makes the brokerage deductions explicit. The “zero-split” example uses a flat $399 brokerage charge as an illustration of the fee structure described in the publisher information. It doesn't represent a mandatory California charge or a universal brokerage price.
California Agent Net on a $750,000 Sale
| Fee Layer | Traditional 70/30 Split | Capped 80/20 + $500 Fee | Zero-Split Flat Fee |
|---|---|---|---|
| Gross agent-side compensation | $19,275 | $19,275 | $19,275 |
| Brokerage percentage retained | $5,782.50 | $3,855 | $0 |
| Flat brokerage charge | $0 | $500 | $399 |
| Illustrative agent net before other expenses | $13,492.50 | $14,920 | $18,876 |
The difference between the first and third columns is $5,383.50 before taxes, insurance, marketing, association costs, and other business expenses. The model with the highest split isn't automatically the strongest choice, because a brokerage may justify its share through mentoring, compliance review, lead distribution, transaction support, brand assets, or office infrastructure.
Which line deserves negotiation
Agents often negotiate the percentage and ignore the fixed charges. That is backwards when production rises. A recurring transaction fee, required technology fee, or mandatory coordination charge can become more important than a small change in the split.
Consumers should also avoid treating the gross percentage as a quality score. The fee pays for an agreed scope of service, not merely access to a listing platform. The right comparison is net proceeds or buyer value against documented work, with all compensation and payment obligations written clearly.
The Non-Commission Fees Most Agents Forget to Budget
The quiet deductions create the most unpleasant surprises because they don't appear in the headline commission discussion. Some are recurring, some occur per transaction, and some are controlled by a local association or service provider rather than the brokerage.
The operating-cost checklist
- MLS and association dues: Access to listing systems and professional association services. These costs may be locally standardized, so an agent should verify the billing schedule rather than assume the brokerage absorbs them.
- E&O insurance: Errors and omissions coverage that helps address professional liability risk. A brokerage may include it, pass it through, or charge a transaction-specific risk-management fee.
- Lockbox access: A practical access expense tied to showing systems and local rules. It can be separate from MLS access.
- Transaction or compliance fees: Charges for file review, document processing, audit readiness, or closing administration. These are among the most important deductions to identify before signing with a brokerage.
- Marketing subscriptions: CRM software, email tools, design platforms, listing advertising, photography, video, and signage. A low brokerage split doesn't help if the agent must independently fund every lead and listing asset.
- Continuing education: Courses and license-maintenance requirements. Training is an expense, but it can also be part of a brokerage's support value.
No verified dollar ranges are provided for these categories, so a responsible comparison should not invent “typical” prices. The better benchmark is the agent's own statement: recurring monthly charges, per-file deductions, annual renewals, and costs paid directly to outside vendors.
Structural versus discretionary costs
Association dues, MLS access, and required insurance are often structural. Agents may have limited ability to remove them, although a brokerage can sometimes bundle or subsidize part of the cost. Marketing subscriptions, premium lead products, client gifts, and optional transaction coordination are more discretionary.
Statement review: Circle every deduction that appears on more than one closing statement. Recurring charges deserve a separate annual budget, not casual treatment as closing noise.
A brokerage comparison should request a sample settlement statement, a complete fee schedule, and a written explanation of when each charge applies. The agent should then calculate net income after all expenses, not compare split percentages in isolation.
How Fees Shift from Los Angeles to the Bay Area and Beyond
California doesn't have one operating environment. A coastal listing, a suburban resale, and an inland transaction may involve different marketing expectations, association structures, travel demands, and client service burdens. The negotiated fee remains the central issue, but the cost of delivering the service changes by market.
The regional comparison below is qualitative because verified data doesn't establish separate operating-cost amounts for Los Angeles, Orange County, the Bay Area, San Diego, or the Inland Empire. Any table that assigns precise local dues or marketing budgets without reliable source data creates false confidence.
Typical California Realtor Operating Costs by Region
| Fee Category | Los Angeles | Orange County | Bay Area | San Diego | Inland Empire |
|---|---|---|---|---|---|
| MLS and association dues | Confirm with the local association and MLS | Confirm locally | Confirm locally | Confirm locally | Confirm locally |
| E&O and brokerage charges | Compare brokerage schedules | Compare brokerage schedules | Compare brokerage schedules | Compare brokerage schedules | Compare brokerage schedules |
| Marketing expectations | Often property and neighborhood specific | Presentation may be a major seller concern | Varies by property segment | Varies by coastal and inland submarkets | Budget travel and geographic coverage carefully |
| Travel and showing burden | Can be significant across wide service areas | Depends on territory | Can be high across dispersed markets | Depends on service area | Often important across broad territories |
| Best comparison metric | Net after all deductions | Net after all deductions | Net after all deductions | Net after all deductions | Net after all deductions |
The same percentage produces a larger gross fee on a higher-priced property, but that doesn't mean the agent's profit automatically rises. Luxury marketing, longer negotiations, complex disclosures, travel, and extended transaction management can consume more time and cash. Inland agents may face a different pressure, with larger geographic coverage and more driving between appointments.
Agents should build separate budgets for each market they serve. A Bay Area agent shouldn't borrow a Los Angeles marketing assumption, and a San Diego agent shouldn't treat an Inland Empire service area as operationally identical.
Consumers should ask for the service plan behind the fee. A fee that includes professional photography, pricing strategy, showing management, offer analysis, and escrow coordination is not equivalent to a lower fee that excludes those responsibilities.
The New Buyer Representation Rules Every Agent Must Follow
The post-2024 system makes compensation a direct contract issue. It no longer works to assume that a buyer agent's fee is embedded in the listing arrangement or automatically supplied through the MLS.
California's Department of Real Estate states that a buyer agent must obtain a signed representation agreement before touring a property. California Assembly Bill 2992, signed on September 24, 2024, added requirements effective January 1, 2025. The agreement must address the agent's compensation, services, when compensation is due, and an expiration date of no more than three months, according to the DRE consumer alert on representation changes.
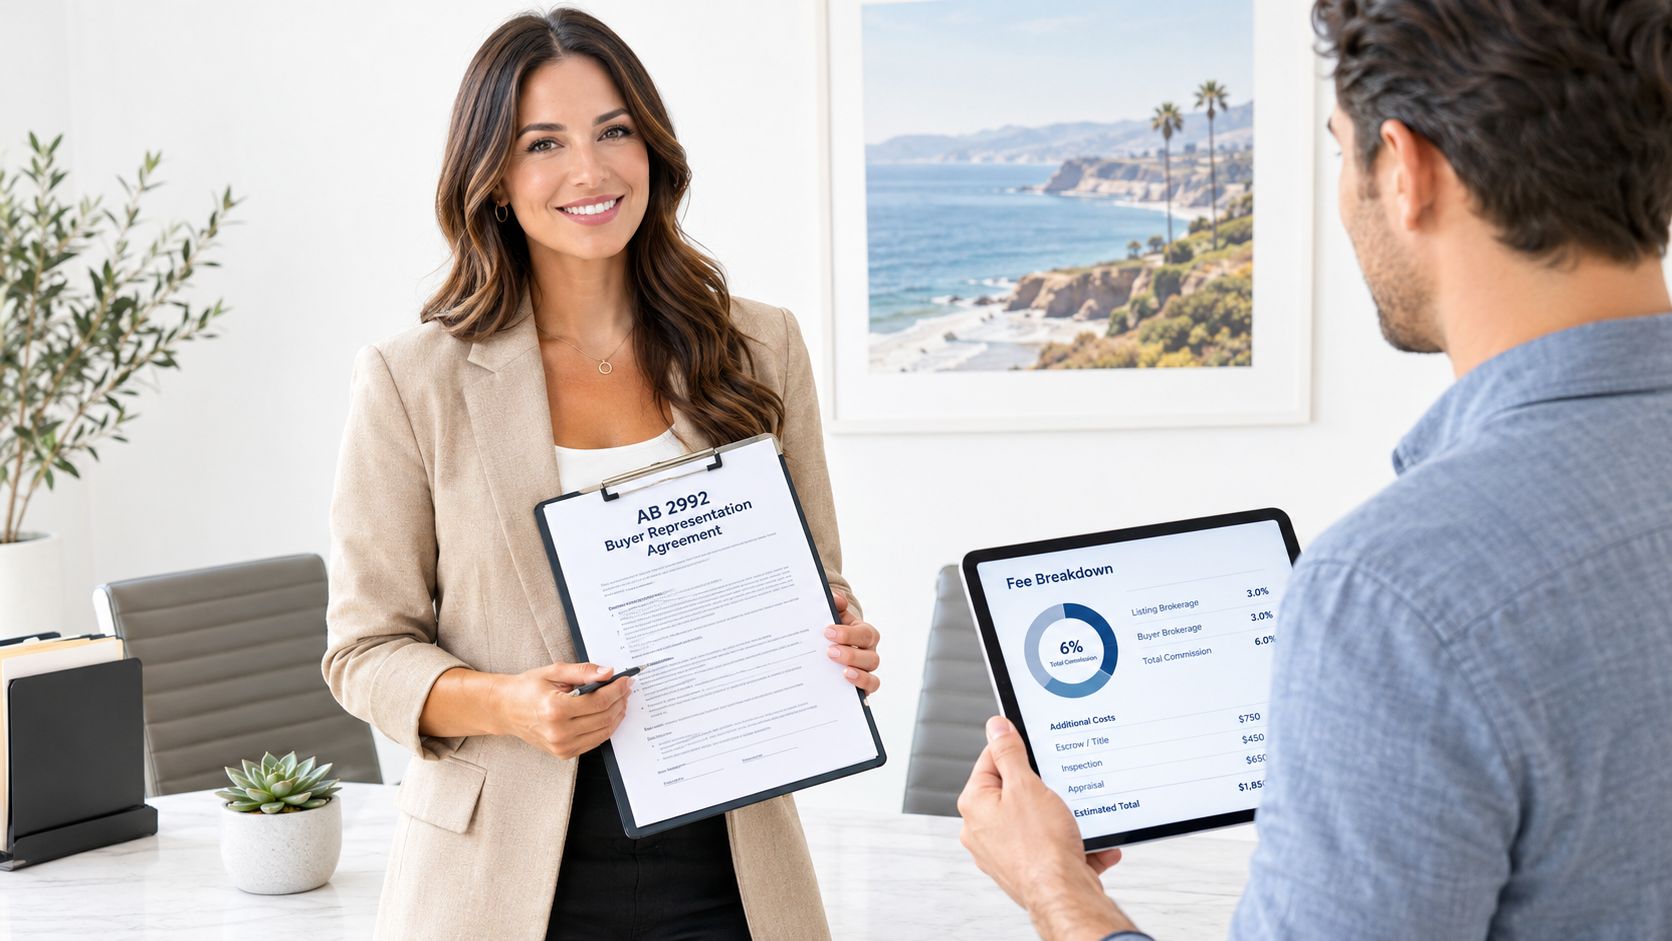
The compensation cap matters
The negotiated compensation in the buyer agreement becomes the maximum the agent may receive from any source for that representation. If the seller or listing broker authorizes less than the buyer's agreed fee, the buyer may owe the difference. If an outside payment exceeds the agreed amount, the agent generally can't keep the excess.
That makes the agreement a fee cap, not a vague promise. The buyer needs to understand the amount, the service scope, payment timing, termination language, and how any seller-paid contribution will be credited.
MLS communication has limits
The National Association of REALTORS® practice changes prohibit offers of buyer-agent compensation from being communicated through the MLS. The parties can still negotiate a seller payment directly, but the seller must authorize it and the transaction documents must reflect the arrangement. The NAR practice-change guidance explains the separation between MLS marketing and direct compensation negotiation.
Agents should use this operational checklist:
- Before the tour: Obtain signatures before showing the property.
- In the agreement: State compensation, services, payment timing, and expiration.
- Before writing the offer: Explain whether the buyer is requesting a seller-paid contribution.
- At closing: Reconcile the agreed fee, authorized payment, and any buyer balance.
- In marketing: Keep buyer-agent compensation out of the MLS compensation field.
Compliance standard: “Whatever the seller offers” isn't a fee schedule. The buyer agreement must establish an objectively understandable maximum.
The reform benefits consumers who compare service and compensation before touring. It also forces agents to explain value earlier, especially when the buyer may be responsible for a shortfall.
Zero-Split and Flat-Fee Brokerages Worth a Second Look
A zero-split model changes the question from “What percentage does the brokerage keep?” to “What fixed costs does the brokerage charge, and what support comes with them?”
Ashby & Graff is one California option that publishes flexible commission plans with transaction fees ranging from $999 to $399 to $99, plus a $145 E&O and risk-management fee for residential transactions up to $1,000,000, according to the publisher-provided brokerage information. Its optional transaction coordination is listed at $550 for single-agency transactions and $700 for dual-agency transactions. These are brokerage-specific terms, not California requirements, and agents should verify the current schedule before joining.
A traditional split can be sensible for a new agent who needs close supervision, lead access, transaction guidance, and hands-on training. The company share may purchase services that would otherwise require separate contractors or mentors. But the value disappears if the agent pays the split and still funds every essential tool independently.
The break-even question
Use the same gross commission, then subtract every cost under each model:
- Traditional split: Lower direct responsibility for infrastructure, but a percentage of each closing goes to the brokerage.
- Capped split: The brokerage retains a percentage until a contractual cap, often with transaction charges before or after the cap.
- Zero-split or flat fee: The agent keeps the commission after a fixed charge, but may assume more responsibility for insurance, compliance, marketing, mentoring, and transaction administration.
The right break-even point depends on the actual fee schedule and production level. A high-volume agent should calculate annual net income across several closings, while a new agent should place a monetary value on accessible broker support.
The low real estate commission model overview can help agents frame the comparison, but the decision should remain contractual. A zero split doesn't eliminate expenses. It reallocates them.
What support is worth paying for
Mentorship, compliance review, training, transaction systems, and a recognizable brand can justify a brokerage charge when agents use them and receive measurable operational value. A flat fee with no practical support may leave an agent exposed to mistakes that cost more than the split would have.
Agents should request the complete fee sheet, ask who pays E&O, identify any cap or reset, and confirm whether direct escrow payment is available. The headline model matters less than the complete closing statement.
A Practical Checklist for Negotiating California Realtor Fees
Agents and consumers should negotiate the scope and economics together. A percentage without a service definition is incomplete.
For consumers
- Request the written fee: Confirm the amount or rate, services, payment timing, expiration, and any possible balance if another party pays less.
- Compare deliverables: Ask whether photography, staging guidance, open houses, offer strategy, inspection support, and escrow coordination are included.
- Model the net: Sellers should review projected proceeds. Buyers should understand the maximum obligation before touring.
- Clarify concessions: Any seller-paid contribution should appear in the transaction documents and should not be treated as an automatic entitlement.
- Read termination terms: A lower fee isn't useful if the agreement makes it difficult to exit an unsuitable relationship.
For agents
- Calculate net, not split: Include brokerage percentages, caps, transaction fees, E&O, MLS costs, marketing, and taxes.
- Ask about support: Identify the broker's response process, compliance review, mentorship, and transaction administration.
- Test volume scenarios: Compare one closing with recurring production. Fixed fees and percentage splits behave differently as volume changes.
- Document client value: Use a clear service menu so negotiation focuses on work and outcomes, not an arbitrary “standard” rate.
- Reconcile at closing: Match the representation agreement, seller authorization, escrow disbursement, and brokerage statement.
The strongest agreement leaves no important payment question for closing day.
Common Fee Questions California Agents Still Ask
Do out-of-state buyers use a different fee structure?
A buyer's residence does not create a separate California rate. Compensation must be negotiated in the written representation agreement before touring, with services, payment timing, and expiration stated clearly under the California framework explained by the Department of Real Estate. Travel, relocation assistance, and remote transaction work belong in the service discussion, not vague wording.
What happens if the seller offers less than the buyer's agreed compensation?
The buyer may owe the difference. The representation agreement sets the maximum compensation and the buyer's contractual obligation. Explain that potential cost before the buyer submits an offer, then document any seller contribution in the transaction paperwork.
Are transaction fees illegal in California?
A transaction fee is not automatically illegal. It must be disclosed, supported by the contract, and consistent with the services and brokerage arrangement. Send any unclear charge to the broker or a California real estate attorney before presenting it to a client.
How often can agents renegotiate a brokerage split?
The brokerage agreement controls. Request a change before signing, at renewal, or when production and support responsibilities materially change. Compare the revised split with transaction fees, support, and your actual closing statement.
Ashby & Graff offers commission plans, zero broker splits, broker support, mentoring, training, and transaction resources. Agents can compare those terms with their current statement at Ashby and Graff.